Projects in Al Warsan
View on map
AED 560K
Information only · We can’t help you buy in this project
AED 450K
Information only · We can’t help you buy in this project
AED 557K
Information only · We can’t help you buy in this project

On request
Information only · We can’t help you buy in this project
AED 488K
Information only · We can’t help you buy in this project
AED 850K
Information only · We can’t help you buy in this project
AED 459K
Information only · We can’t help you buy in this project
AED 772K
Information only · We can’t help you buy in this project
AED 525K
Information only · We can’t help you buy in this project
On request
Information only · We can’t help you buy in this project
Nearby Projects
- New Projects in International City Phase 2 (Al Warsan 4)
- New Projects in International City
- New Projects in Dubai Silicon Oasis
- New Projects in Nadd Al Hammar
- New Projects in Liwan
- New Projects in Ras Al Khor
- New Projects in Al Rowaiyah 1
- New Projects in Dubai Land Residence Complex
- New Projects in Dubai Land
- New Projects in Dubai Creek Harbour (The Lagoons)
- New Projects in Haven By Aldar
- New Projects in Bukadra
- New Projects in Wadi Al Safa 5
- New Projects in Mohammed Bin Rashid City
- New Projects in Falcon City of Wonders
Other Developers
- New Projects by Al Helal Al Zahaby Real Estate
- New Projects by Anax Developments
- New Projects by Meraas Holding
- New Projects by LEOS International
- New Projects by Dugasta
- New Projects by Samana Developers
- New Projects by Valores Property Development
- New Projects by Laraix Developers
- New Projects by JHK Developments
- New Projects by Jewel Development
- New Projects by Newbury Development
- New Projects by AJG
- New Projects by B.N.H Developer
- New Projects by Ayat Development
- New Projects by Park Group
Apartments, Affordability, and a Crowded Builder Market: New Projects in Al Warsan
Al Warsan is a residential district within Dubai with a significant volume of active off-plan apartment listings. Its two sub-areas, Al Warsan 1 and Al Warsan 4, account for most of the market activity. Prices start below AED 500,000, the developer count is high relative to total projects, and the property mix is almost entirely apartments. Each of those features has implications for how buyers should approach this market.
AED 543K as the Midpoint of a Wide Range
The price median across current listings is AED 543,000. That is the most useful number for a buyer setting a realistic budget. The floor sits at AED 450,000 and the ceiling reaches AED 1,754,861, a more than three-to-one spread that points to genuine product variety within the district.
The property mix reinforces the apartment focus: 27 confirmed apartment projects alongside a single penthouse listing. With apartments accounting for nearly the entire supply, this is primarily a market for buyers and investors focused on that product type. The penthouse entry represents one atypical listing at the high end of the pricing range.
25 Developers Across 31 Projects
25 developers are active across 31 projects, averaging close to one developer per project. Most names on the list are smaller operators: Al Helal Al Zahaby Real Estate, JHK Developments, Jewel Development, Laraix Developers, Newbury Development, Valores Property Development, Dugasta, Gulab Developments, Amber Developments, Anax Developments, and others. A small number of larger names also appear, including Samana Developers, Meraas Holding, and LEOS International.
For a buyer, this level of fragmentation has direct consequences. Build quality and delivery track records vary considerably across smaller developers, and those reputations are harder to assess quickly. Resale liquidity can also be thinner when no single developer holds meaningful brand presence in a district. In this kind of market, due diligence on individual operator track records carries more weight than brand name alone.
A Handover Window Running to Late 2029
The earliest completion date recorded across current listings is August 2024. Some projects are likely already handed over, and buyers should verify construction and availability status directly before committing. Listing data does not always reflect real-time delivery progress.
The latest scheduled completion runs to November 2029, roughly four years out. That is the full off-plan commitment horizon for buyers entering at the far end of the available inventory. Projects with 2025 or 2026 handover dates offer earlier possession for those who prefer not to wait out the longer timeline.
Low Entry, Post-Handover on Nearly a Quarter of Listings
Down payment requirements start at 5%, which is a low entry point for Dubai off-plan. It allows buyers to enter the market with limited upfront capital.
7 of the 31 projects include post-handover payment plans, accounting for roughly 23% of current listings. These plans spread the remaining balance over a period after keys are transferred rather than requiring full settlement at completion. For an investor managing cash flow against expected rental income, the structure of a post-handover plan changes the financial timeline of the investment in a concrete way.
Security and Family Amenities Across the Board
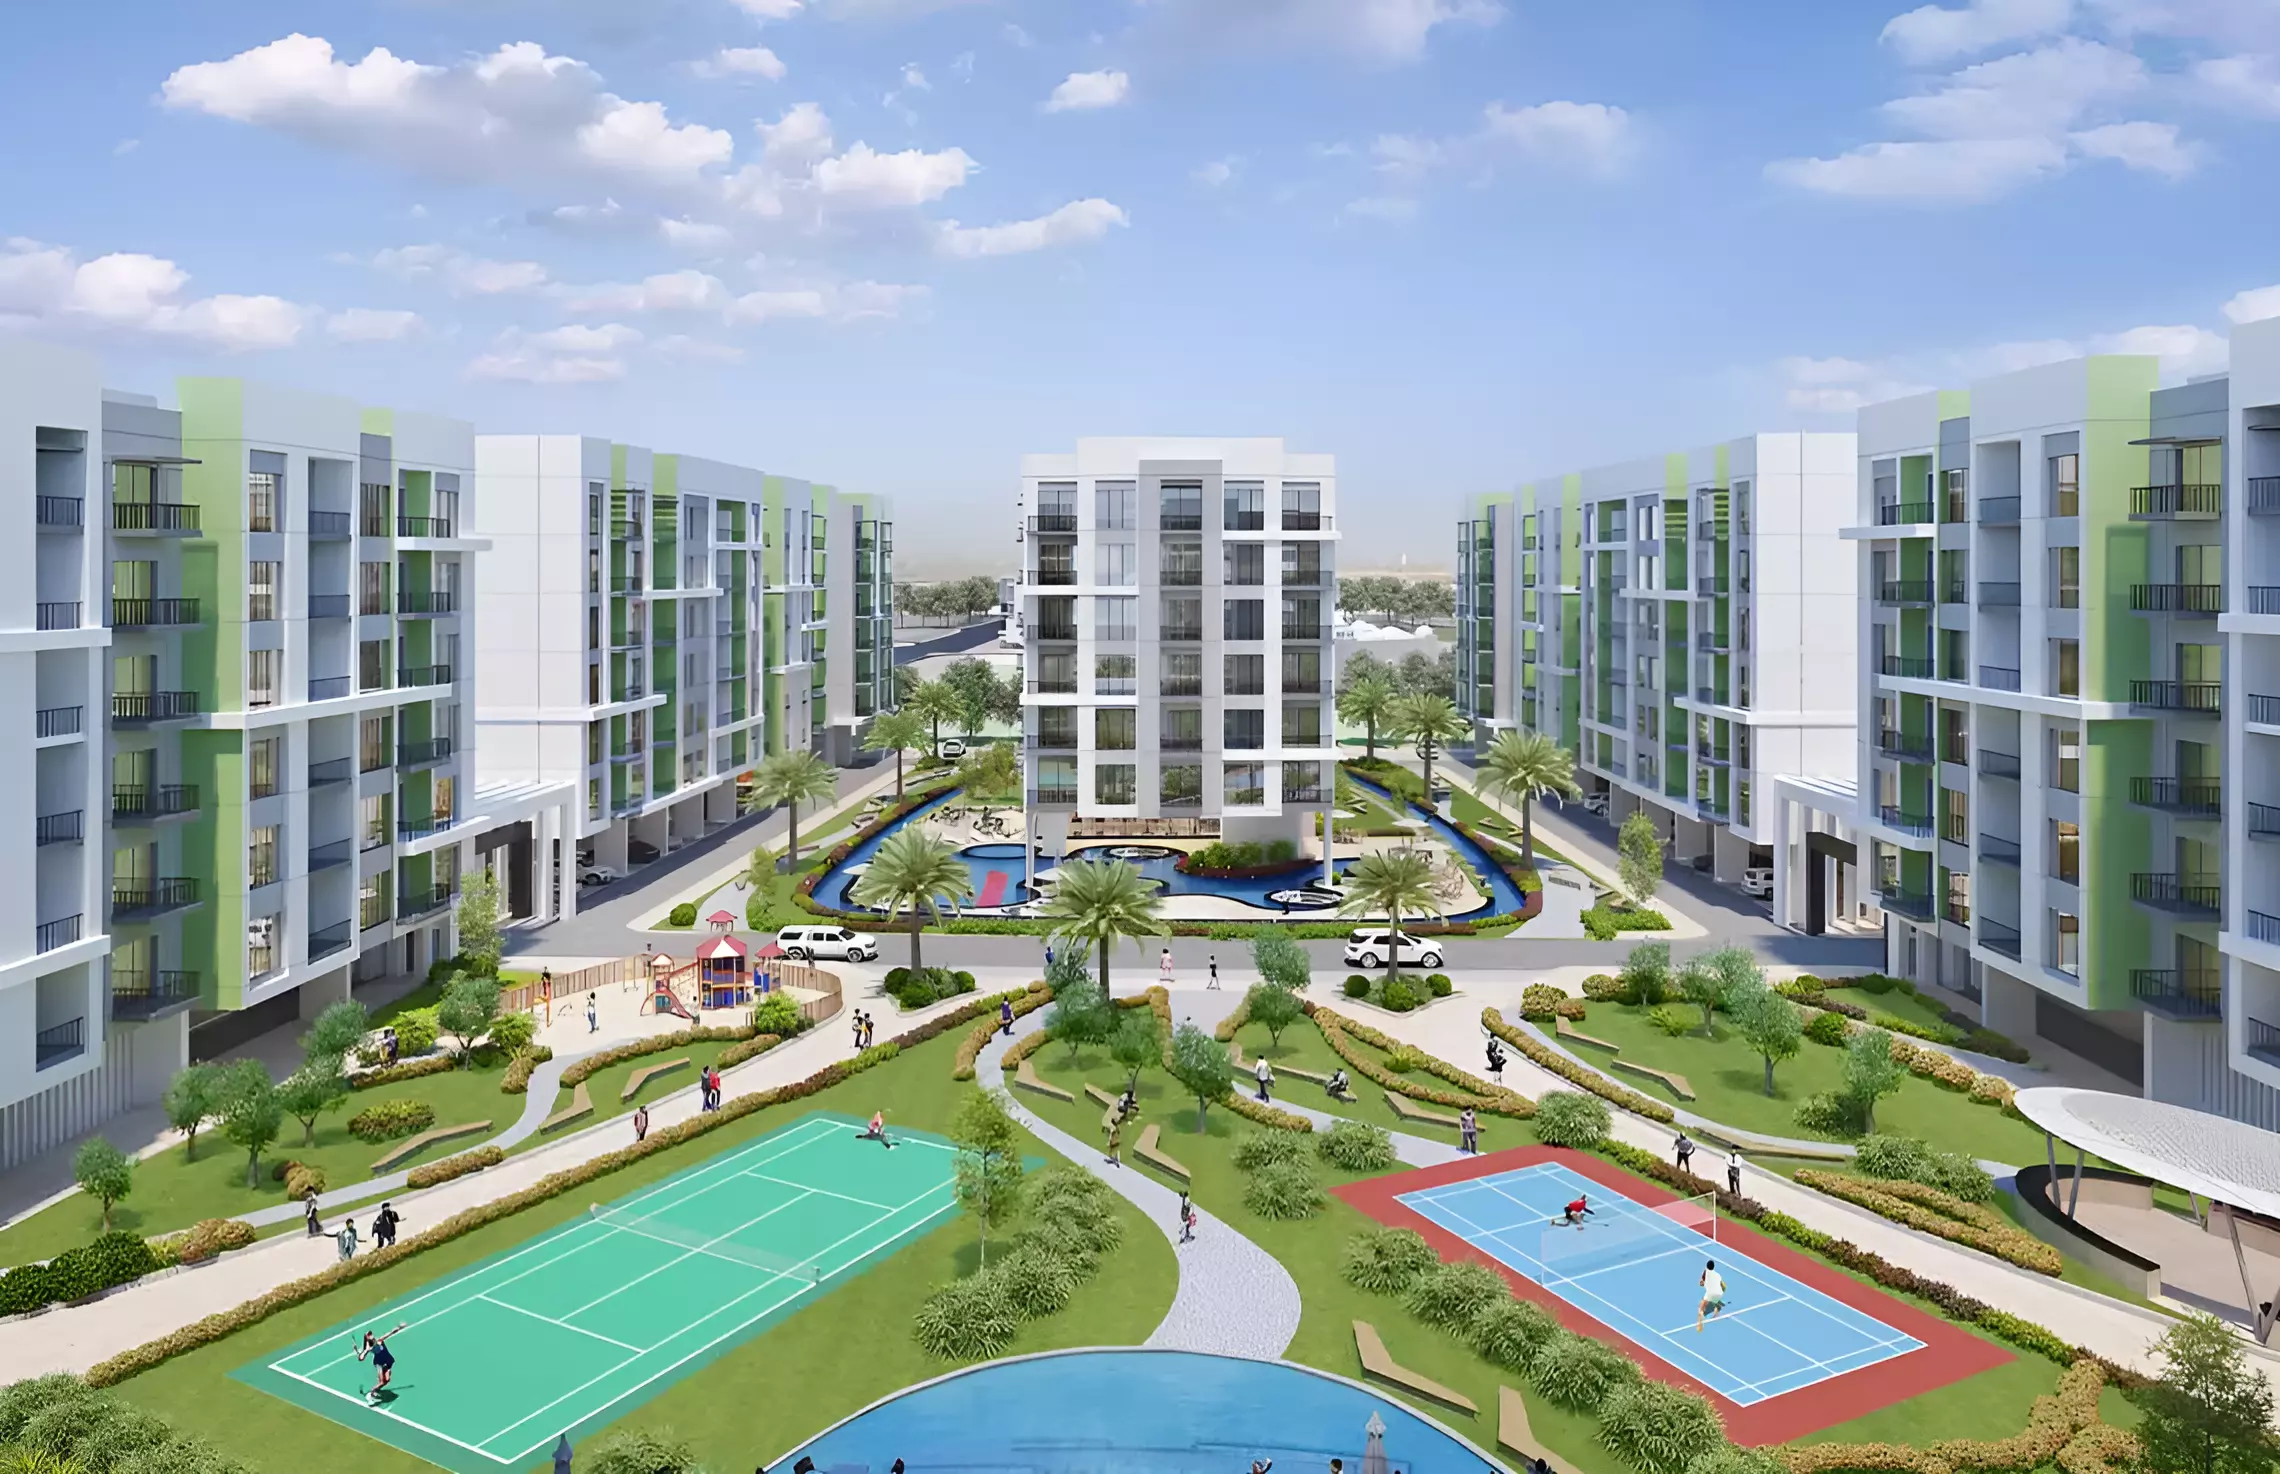
The amenity pattern across Al Warsan projects is consistent. Children's play areas, gymnasiums, indoor swimming pools, and landscaped gardens appear across multiple listings, alongside CCTV monitoring and security provisions. Taken together, those choices point toward a resident profile of families and long-term occupants rather than short-stay renters or premium lifestyle buyers.
Retail facilities and covered parking appear frequently as well, reinforcing a practical, everyday-convenience focus. The area does not position itself around spa amenities, rooftop features, or luxury-tier infrastructure. Buyers whose priorities are family-oriented facilities, security, and day-to-day convenience will find the amenity set well matched to those needs.